Home › Applied › Financial Derivatives Pricing

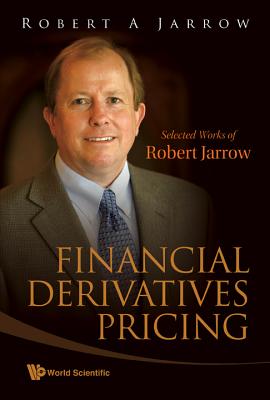
Financial Derivatives Pricing

by Jarrow Robert a

Research papers on derivatives pricing

Regular price $235.96 USD
Regular price $262.18 USD Sale price $235.96 USD
Save 10%

Hardcover New English

Delivery to your door
In stock·Dispatches in 1–2 business days
Standard shipping* from $4.35
Standard shipping transit* 5–8 business days after dispatch

Faster options are available.

Rates and delivery estimates depend on your destination and item quantity. Estimates are informational only; the final shipping method and rate are selected at checkout.

Secure checkout
American Express Apple Pay DiscoverGoogle Pay Mastercard PayPalVisa
30-day eligible returns Returns & refunds policy

AlbakiReads Editorial

Research papers on derivatives pricing

Robert Jarrow’s collected papers trace several strands of financial derivatives research across three sections. The first examines option-pricing theory, including the Black–Scholes–Merton model, American put options, and arbitrage pricing applications to market manipulation and liquidity risk. The second turns to stochastic interest rates, presenting the Heath–Jarrow–Morton model alongside work on forward and futures prices and applications involving currencies and commodities. The final section brings interest-rate uncertainty together with default risk, covering reduced-form credit models, credit-rating transitions, counterparty risk, and diversifiable default risk. Together, the sections provide a research-oriented overview of how these pricing questions are framed and connected.

Good fit for readers who enjoy

  • Readers studying mathematical finance or financial economics.
  • Researchers interested in option pricing and arbitrage pricing theory.
  • Readers seeking collected research on stochastic rates and credit risk.

Themes

Option pricingArbitrage pricing theoryStochastic interest ratesCredit and default risk

Based on publisher information and book metadata.

Book overview

This book is a collection of original papers by Robert Jarrow that contributed to significant advances in financial economics. Divided into three parts, Part I concerns option pricing theory and its foundations. The papers here deal with the famous Black-Scholes-Merton model, characterizations of the American put option, and the first applications of arbitrage pricing theory to market manipulation and liquidity risk.

Part II relates to pricing derivatives under stochastic interest rates. Included is the paper introducing the famous Heath-Jarrow-Morton (HJM) model, together with papers on topics like the characterization of the difference between forward and futures prices, the forward price martingale measure, and applications of the HJM model to foreign currencies and commodities.

Part III deals with the pricing of financial derivatives considering both stochastic interest rates and the likelihood of default. Papers cover the reduced form credit risk model, in particular the original Jarrow and Turnbull model, the Markov model for credit rating transitions, counterparty risk, and diversifiable default risk.

Shipping & returnsShipping options, delivery timing, and our return policy.

In-stock items normally dispatch within 1–2 business days. The ZIP-code estimator on this page is informational only; the final shipping method, price, and availability are confirmed at checkout for your full order.

For the initial delivery estimate we use these transit windows after dispatch: Standard 5–8 business days, Expedited 2–4 business days, and Priority 1–2 business days. Holiday delays are not included.

Eligible items can be returned within 30 days in accordance with our return policy.

Customer reviews